
19 min read
19 min read
So, how hard is it to get a home equity loan?
For some homeowners, the process can be fairly straightforward. If you have enough usable equity, steady qualifying income, manageable monthly debt, and a reasonably strong credit history, you may have a solid starting point. Things get more complicated when one or more of those pieces are weak.
The biggest misconception is that owning a large amount of equity automatically gets you approved. It doesn't. A home equity loan is typically a lump-sum loan secured by your home. If you already have a mortgage, the new loan generally sits behind it as a junior lien. Many home equity loans have fixed rates, which means you'll usually make a predictable monthly payment over the loan term.
The Consumer Financial Protection Bureau also distinguishes a home equity loan from a HELOC, which generally gives you access to a revolving line of credit rather than one upfront lump sum. That distinction matters when you're deciding how hard is it to get a home equity loan because the underwriting and product structure can vary.
If you're comparing products, Truss Financial Group's HEI vs. HELOC vs. Home Equity Loan is a useful place to start.
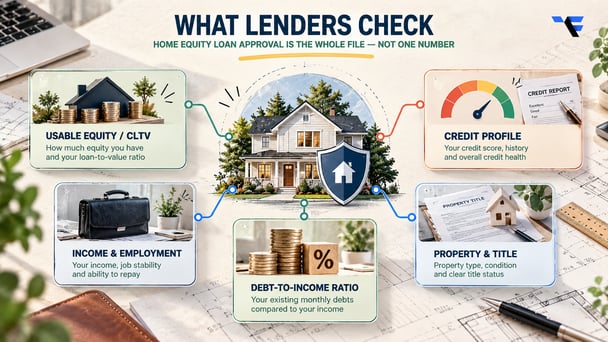
Lenders don't assess your application based on one number. They look at how several pieces fit together.
| Approval factor | What the lender is checking | What can make approval harder |
|---|---|---|
| Usable equity/CLTV | Existing mortgage balances and the proposed loan compared with property value | Low equity cushion or lower-than-expected appraisal |
| Credit profile | Payment history, scores, recent delinquencies, and overall credit risk | Late payments, collections, bankruptcy, or limited credit |
| Income and employment | Whether income is stable, documentable, and likely to continue | Variable income, declining income, or incomplete records |
| Debt-to-income ratio | Existing monthly obligations compared with qualifying gross income | Large credit card, auto, student loan, housing, or support payments |
| Property and title | Whether the property and ownership structure meet program requirements | Unreleased liens, title problems, unusual property, or insurance issues |
The Federal Reserve's guidance on home equity lending also highlights factors such as credit risk, loan-to-value exposure, property characteristics, and underwriting documentation when lenders evaluate risk. In other words, how hard is it to get a home equity loan depends on the strength of the entire file, not just your home's equity.
Explore your home equity options with Truss Financial Group today.
Before worrying about credit scores or paperwork, look at the equity itself. Your equity is essentially the difference between your home's current value and what you still owe against it. But you generally can't borrow all of that difference.
That's where LTV and CLTV come in. LTV, or loan-to-value ratio, compares a loan balance with the property's value. CLTV, or combined loan-to-value ratio, considers multiple liens. When you already have a first mortgage and want a home equity loan behind it, CLTV is usually the more useful number.
Here's a simple example.
Suppose your home is worth $400,000. You owe $260,000 on the first mortgage and want a $40,000 home equity loan. Your combined debt would be $300,000. That gives you a 75% CLTV.
Whether that works depends on the lender's maximum CLTV, minimum loan amount, property requirements, and the rest of your financial profile. A lender may also use a different property valuation than the number you've estimated.
There isn't one universal checklist that every lender follows. The home equity loan requirements can vary depending on the lender, property, lien position, loan amount, occupancy, and borrower profile.
Lenders can look at your score, but they also care about how you've handled debt. A few older blemishes may be viewed differently from several recent missed payments. You may see a home equity loan credit score benchmark of around 620 mentioned in lender or consumer-finance guidance. Treat that as an example, not a federal rule. Some programs may require a higher score, while others may consider additional factors.
To qualify for a home equity loan, you generally need to show that the proposed payment fits within your overall financial picture. W-2 employees may have relatively straightforward documentation, while self-employed borrowers or people with variable income may need to provide additional records.
Your home equity loan DTI is essentially a comparison between qualifying monthly debt obligations and gross monthly income. A lender may look for a debt-to-income ratio around the low-to-mid 40% range, but that is not a universal cutoff. A lower home equity loan DTI can make the repayment picture easier to support. A higher one may make the application more difficult, particularly if there are other risk factors.
Property value, homeowners insurance, title, and your existing mortgage payment history can also come into play. These home equity loan requirements work together. A strong file may sometimes offset a borderline factor, while several weaker factors can compound each other.
There's no single answer to how hard is it to get a home equity loan because two homeowners with the same amount of equity can have completely different applications.
A home equity loan denial can happen for several reasons, and the reason isn't always obvious from the amount of equity you have. Common problems include:
If you receive a home equity loan denial, don't automatically assume your finances are the only issue. Review the reason the lender provided. An adverse action notice can explain the principal reason or reasons for the decision, subject to applicable requirements. That information can help you determine whether the problem is something you can correct or simply a limitation of that particular loan program. (Consumer Financial Protection Bureau)
The process usually starts well before you submit an application.
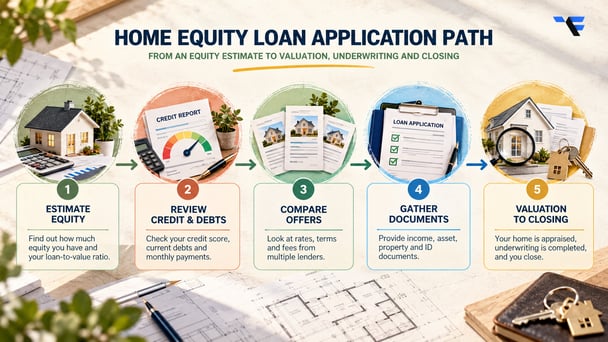
There isn't a universal timeline for how long all of this takes. A straightforward file can move differently from one that requires extra income documentation, a title correction, or additional property review.
Home equity loans can come with costs beyond the interest rate. Depending on the lender and transaction, you may encounter origination charges, appraisal or valuation costs, title fees, recording charges, and other lender or third-party expenses.
Some lenders may cover or waive certain costs, sometimes subject to specific conditions. Read the offer carefully rather than assuming a zero-upfront-cost option is automatically cheaper. There's also the monthly payment to consider. A fixed payment can make budgeting easier, but financing fees mean you're paying interest on a larger balance if those costs are added to the loan.
And then there's the biggest risk: your home is collateral. If you stop making payments, the lender can have rights against the property. The Consumer Financial Protection Bureau specifically notes that failure to repay a home equity loan can put the home at risk.
Tax treatment needs similar caution. The IRS says interest on home equity debt generally isn't deductible when the proceeds are used for purposes other than buying, building, or substantially improving the qualified home securing the debt, subject to applicable rules and limits. Your individual situation can differ, so speak with a qualified tax professional before assuming the interest is deductible.
You don't have to fix every part of your financial life before applying. Focus on the factors that are most likely to affect the actual underwriting decision.
Truss Financial Group's using home equity to pay off debt can also help if debt consolidation is part of your reason for borrowing.
A home equity loan isn't the only way to tap home equity. A HELOC may make more sense when you expect to need money over time rather than all at once. Instead of receiving one lump sum, you generally get a revolving line of credit and draw funds as needed. HELOCs typically have variable rates, so payment and interest costs can change.
A cash-out refinance is another possibility. Instead of adding a second lien, you replace the existing mortgage with a larger one and receive the difference as cash. Whether that makes sense depends heavily on your existing mortgage rate, the new loan's terms, closing costs, and how long you expect to keep the loan.
Then there's an unsecured personal loan. It doesn't put your house up as collateral, although borrowing limits, rates, and repayment terms can differ substantially. Don't choose based solely on the lowest advertised rate. The total cost, payment structure, fees, repayment period, and risk to your home all deserve a place in the comparison.
It can be relatively straightforward when you have sufficient equity, stable qualifying income, manageable debt, and acceptable credit. But owning a home with substantial equity isn't enough by itself. The lender still needs to determine whether you can comfortably repay the loan and whether the property provides sufficient collateral.
There's no responsible way to give an individual approval percentage without reviewing the complete application. Your equity, existing liens, credit history, income, debts, property, documentation, and the lender's program all play a role. Someone asking how hard is it to get a home equity loan should therefore look at the entire financial picture rather than focus on a single score or equity figure.
Possibly, although choices can become more limited. Depending on the lender and circumstances, you may face higher pricing, lower available proceeds, or stricter requirements. There isn't one universal credit score that automatically determines whether you qualify for a home equity loan.
Yes. A home equity loan denial can happen because of insufficient equity, high DTI, credit problems, unverifiable income, title issues, property restrictions, or incomplete documentation. If you've received a home equity loan denial, look at the lender's stated reason before deciding what to do next. You may be dealing with a correctable issue rather than an across-the-board inability to borrow.
Not necessarily in the traditional sense. The lender does need a reliable way to establish the property's value, but that doesn't always mean a full in-person appraisal. Depending on the transaction and applicable requirements, the lender may use an automated valuation model, exterior review, broker price opinion, full appraisal, or another permitted method.
Yes. A paid-off property can potentially be used as collateral for a home equity loan. Having no first mortgage may simplify the lien structure, but it doesn't remove the normal credit, income, property, title, and repayment requirements. You still need to qualify for a home equity loan based on the lender's program.
The biggest concern is that the loan is secured by your home. If you cannot make the required payments, the property can be at risk. You also need to consider the added monthly obligation, closing costs, and total interest over the life of the loan. Before borrowing, make sure the payment fits comfortably within your budget rather than focusing only on how much equity you can access.
So, how hard is it to get a home equity loan?
There's no single cutoff that answers the question for every homeowner. What matters is the combination of usable equity, CLTV, credit, income, DTI, property eligibility, title, and the lender's own rules.
Before you apply, run the numbers. Check your credit. Gather your income documents. Look at your existing debts and estimate your CLTV. If something looks weak, you'll have a better chance of addressing it before underwriting starts.
Truss Financial Group can review your equity, income, credit profile, and intended use of funds and help you compare available options. Any approval, rate, loan amount, or terms remain subject to applicable lender and program requirements.


Take your pick of loans
Experience a clear, stress-free loan process with personalized service and expert guidance.
Get a quote
10 min

10 min

15 min
Discover your borrowing power and plan your mortgage journey with knowledge on your side.
Get a quoteGet a quote in 3 easy steps
Tell us what you want
Fill out our online form to help us understand your financial situation and loan needs.
We get to work for you
We review your info and look for competitive rates that match your specific goals.
You get a personalized quote
You’ll receive a customized rate quote that meets your unique profile.