
16 min read
16 min read
If you’re pursuing a 90 LTV home equity loan, read this blog to understand how it relates to a second lien. With regard to financing considerations, a second-lien loan may entail combined loan-to-value (CLTV) underwriting, which includes first mortgage indebtedness and the requested second lien.
A 90 LTV home equity loan may sometimes be available to qualifying borrowers subject to credit, DTI, property, occupancy, lien position, valuation, and other criteria. Truss Financial Group can assist shoppers with regard to equity assessment and structure comparisons, which also appear in a HEI vs. HELOC vs. Home Equity Loan comparison.
A 90 percent CLTV home equity loan involves a closed-end second mortgage in which combined debts may equal approximately 90% of the value of the collateralized property, subject to the applicable program.
Standard LTV calculations typically involve one outstanding loan. For example, if indebtedness of $300,000 on a $500,000 home equals $500,000 and your first mortgage balance is $300,000, the LTV would equal 60%.
With regard to a second mortgage, the difference between a line of credit and a home equity loan also becomes relevant. The expression home equity loan 90 LTV can be misleading if it implies that the second mortgage would equal 90 percent of the value of the property.
According to the Federal Reserve, the agencies view residential lending "at or above 90% of the appraised value of the dwelling" as high LTV lending and consider the "additional collateral risk" associated with such lending arrangements.
Consider the following comparison.
| Measure | Simple formula | What it tells the lender |
|---|---|---|
| LTV (Loan-to-Value) | One loan balance ÷ property value | How large one loan is relative to the home's value |
| CLTV (Combined Loan-to-Value) | (Existing mortgage balances + proposed closed-end loan) ÷ property value | How much total mortgage debt is secured by the property |
| HCLTV (Home Equity Combined Loan-to-Value) | (Mortgage balances + full available HELOC limit) ÷ property value | Total exposure when a revolving credit line is involved |
With regard to a second loan, CLTV typically applies. With regard to a HELOC, the lender may apply HCLTV, particularly if the borrower draws upon the line.
The math isn't complicated.
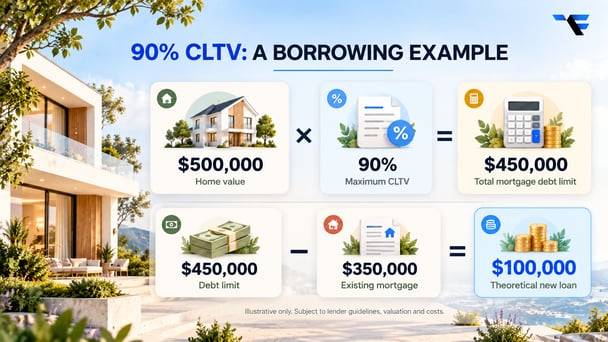
Property value × maximum CLTV − existing mortgage and other included liens = theoretical maximum new loan.
Let's go back to that $500,000 property.
At a 90% maximum CLTV:
$500,000 × 0.90 = $450,000
If the existing mortgage balance is $350,000:
$450,000 − $350,000 = $100,000
So, on paper, you could have room for a $100,000 second loan.
This calculation is theoretical. This makes it important to understand HELOC vs. home equity loan differences. The lender may offer less due to credit, DTI, underwriting, property guidelines, valuation, and reserves.
Using the sample calculations, a $500,000 home is valued at $360,000; a home with no first mortgage may produce a similar result if the lender offers a HELOC. For details, homeowners with paid-off residences may wish to consult TFG's paid-off home HELOC guide.
A 90 LTV home equity loan is available to some borrowers, but not all lenders make such products available to all borrowers due to credit, DTI, occupancy, and other considerations. According to federal bank regulators, elevated LTV and DTI ratios are risk factors for home equity lending. Lenders may consider credit, DTI, income, value, occupancy, lien position, and reserves when considering a second mortgage. Further information appears in TFG's HELOC approval guide.
There is no one-size-fits-all formula with regard to a home equity loan 90 LTV. The lender may consider credit, DTI, income, value, occupancy and other considerations. The property value can make a significant difference.
Suppose the total debt is $ 418,500. With a $465,000 home and a 90 percent CLTV home equity loan, the theoretical borrowing capacity for a $350,000 first mortgage would equal $68,500.
Lenders typically consider a number of variables when establishing home equity loan rates.
For example, the 90 LTV percentage itself is one factor among many. Other variables may include term, size, use, occupancy, and collateral characteristics.
A 90% LTV home equity loan may involve a higher rate than a 70% or 8% CLTV product, since the lender faces more risk with regard to a higher LTV. As noted by the FRB, elevated LTV and DTI are risk factors with regard to home equity lending.
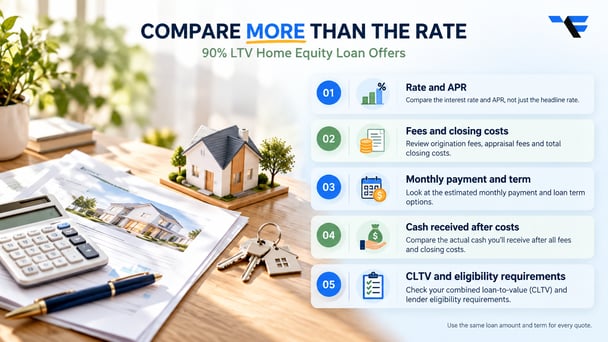
Review the rate, APR, fees, payment, and term. When comparing offers, consider the total dollar amount rather than the rate. With regard to a home equity loan 90 LTV interest rate, the quote may involve points or other considerations that change the picture.
Expenses typically include origination, appraisal, title, recording, and closing costs. These may include points, credit report, and flood certification if applicable. A no-closing-cost arrangement typically involves costs in another form.
According to the FTC, consumers should review the closing costs and the terms of the agreement before proceeding. If the arrangement involves fees and APR, those would be material terms. Lenders may finance certain costs as part of the total amount due. At 90% LTV, additional costs may reduce equity significantly.
| Leverage | Potential Advantage | Tradeoff |
|---|---|---|
| 80% or lower | More equity remains in the property and pricing may be stronger | You may receive less cash |
| Around 85% | A middle ground between proceeds and retained equity | Still subject to lender-specific pricing and eligibility |
| Up to 90% | More potential borrowing from the same property value | Less equity cushion and potentially tighter underwriting |
A high LTV home equity loan can maximize cash, but a high LTV home equity loan reduces equity, which is important if selling or refinancing the residence soon.
A home equity loan is a lump sum. This option may offer a fixed rate and predictable monthly payment, which can be useful for specific needs, such as funding a major purchase.
A HELOC is a line of credit. TFG discusses a HELOC as a second mortgage. This option offers more flexibility, since the borrower can draw on it as needed. The interest rate tends to be variable, and payments change depending on the amount of the outstanding loan.
With a cash-out refinance, the borrower replaces the existing first mortgage with a higher first mortgage and receives the difference in cash.
For cash-out refinance and other home equity loan 90 LTV options, discuss the alternatives with Truss Financial Group.
If shopping for a 90 LTV second mortgage or cash-out refinance, Truss Financial Group can provide a general evaluation. In addition to CLTV considerations and guidelines, compare rate, term, and cash due, as well as the overall equity position.
The single greatest risk with a 90% home equity loan is reduced equity that may limit options in the future. A high LTV home equity loan involves fewer reserves at the time of a refinance or sale.
If the property value decreases, the homeowner may have limited options compared to someone with higher equity. If the homeowner sells the home, the net proceeds must pay off any liens after closing costs.
The owner has a secured loan against the real property. In the case of default, the lender may pursue the collateral. For details, refer to the CFPB regarding repayment options for home equity loans.
Before choosing a lender, get the same information from each one. Otherwise, comparing offers can become an apples-to-oranges exercise.
For a 90 ltv home equity loan, ask:
Using the same loan amount and term for every quote makes the comparison much more useful.
Lenders may use combined loan-to-value as an underwriting guideline when considering a second mortgage. A 90, home equity loan usually refers to the CLTV, not the second mortgage LTV. It means that the amount already owed on the home divided by the value of the home, including the second mortgage, equals 90 percent.
90 percent home equity loan can be a higher percentage when compared to a mortgage with 70 percent or 80 percent LTV. The FRB has specific guidance with regard to high loan-to-value mortgages.
There is no absolute standard with regard to credit scores. Lenders may have minimum standards that apply to bad credit home equity loans or HELOCs. At the same time, higher percentages and bad credit can combine to limit the shopper's options and increase prices.
The highest leverage typically does not exceed 95 percent. In some special circumstances, certain lenders may make 100 percent home equity loans available.
A lower appraisal reduces the value of the collateral, which limits the amount the lender would be willing to lend at the specified CLTV.
These are two different considerations: A home equity loan is a closed-end second mortgage, while a HELOC is a line of credit. At the same time, the HELOC may involve maximum leverage. A 90 percent HELOC is expressed as a maximum HCLTV.
Lenders vary with regard to criteria, and eligibility depends on the borrower's credit, income, DTI, occupancy, and collateral, as well as the proposed loan amount and structure. In the appropriate case, request a quote.
Interest rates and APRs vary, and time is of the essence. Rate shopping helps, and rate comparisons should be done on the same day for the same loan amount. Ensure that the rate quotes apply to the same loan-to-value percentages. Consider the interest rates on cash-out refinances, home equity loans, and other second mortgage products.
Tax deductions are not automatic. The IRS observes the following with regard to home equity loans.
"For tax years beginning after 2017, you can deduct interest on home equity loans if the loan proceeds were used to buy, build, or substantially improve the home. Otherwise, your home equity loan interest will not be deductible."
Personal expenses typically do not apply. The IRS observes the following: "You generally cannot deduct interest paid or accrued on a credit card or other open-end credit."
For details regarding home equity loan interest deductions, review IRS Publication 936 and consult with a tax professional at Truss Financial Group.


Take your pick of loans
Experience a clear, stress-free loan process with personalized service and expert guidance.
Get a quote
17 min

15 min

15 min
Discover your borrowing power and plan your mortgage journey with knowledge on your side.
Get a quoteGet a quote in 3 easy steps
Tell us what you want
Fill out our online form to help us understand your financial situation and loan needs.
We get to work for you
We review your info and look for competitive rates that match your specific goals.
You get a personalized quote
You’ll receive a customized rate quote that meets your unique profile.