View all states
First Time Home Buyer Challenges: What to Know

12 mins
In this blog
Buying your first home involves exciting opportunities and many details to manage. Major first-time home buyer challenges usually fall into the categories of affordability, having enough money saved, qualifying for financing, choosing the right home, and navigating from accepted offer to closing.
For many buyers, preparation beats perfection. These first-time home buyer challenges are more manageable when you understand where to focus. More first-time home buyer challenges can arise as you begin to consider financing options. Truss Financial Group can help you understand your financing options, and its first-time home buyer qualifications guide can help you understand what factors a lender may consider before you begin to shop.
Setting a Budget That Covers the Full Cost of Ownership
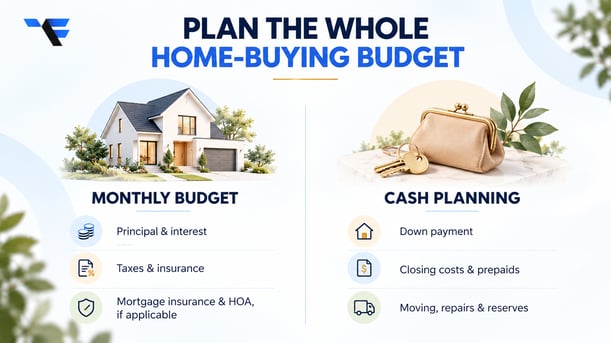
One of the most common challenges for first-time home buyers is thinking that the monthly mortgage payment is the entire cost of homeownership. Other first-time home buyer challenges include understanding the true cost of taxes and insurance.
The principal and interest are only part of the equation. Depending on the home and financing, a monthly housing payment can also include property taxes, homeowners insurance, mortgage insurance, and HOA dues.
A $350,000 home with 10% down and a $315,000 mortgage at an illustrative 6.50% 30-year fixed rate would have a principal and interest payment of approximately $1,991 per month. Add $400 in taxes, $150 for insurance, and $150 for mortgage insurance. The illustrative total becomes about $2,691.
| Cost Item | Illustrative Monthly Amount |
|---|---|
| Principal and interest | $1,991 |
| Property taxes | $400 |
| Homeowners insurance | $150 |
| Mortgage insurance/other charge | $150 |
| Total housing payment | $2,691 |
Note: These figures are illustrative.
Set a realistic budget for utilities, upkeep, repairs, commuting, and general household expenses. Establish a cash reserve for moving and emergencies. One of the best first-time home buyer tips is to establish a personal spending limit before a lender establishes your borrowing limit. Eligibility and affordability are two separate issues.
Saving for the Down Payment and Cash to Close
A down payment is a separate issue from cash to close. Cash to close can include the closing costs, prepaid items, and an escrow deposit, along with any other expenses. Seller credits and lender credits can also affect the amount.
This is one of the major first-time homebuyer mistakes that can lead to a last-minute surprise. If you have $40,000 saved, you cannot automatically treat all $40,000 as a down payment.
According to the CFPB, closing costs typically range from 2% to 5% of the home price (not including the down payment). This is among the common challenges faced by first-time home buyers – many first-time home buyers do not budget for expenses beyond the negotiated price.
You should also assume that you may not need to contribute 20% for a down payment. Freddie Mac notes that certain conventional programs can allow eligible buyers to put as little as 3% down. A lower down payment can affect the loan amount and may require mortgage insurance.
A 3% minimum down payment is not necessarily the best option for every buyer. The right down payment depends on your overall cash position and budget. One of the first-time home buyer mistakes to avoid is to think that the down payment is your total home-buying budget. Always set aside an emergency fund.
Inquire about first-time homebuyer assistance programs in your state or local area and HUD-approved housing counseling. Availability, eligibility, funding, lender participation, repayment terms, and other conditions can vary.
Qualifying With Limited Credit History or Variable Income
Credit History and Existing Debt
Credit history and recurring debt can impact your mortgage eligibility and pricing. A lender may also calculate your debt-to-income ratio (DTI). The CFPB defines DTI as the amount of monthly debt payments divided by gross monthly income.
Using $2,400 in monthly debt against $7,000 in gross income as an example, the DTI would be approximately 34%. The housing payment may factor into this calculation.
Examine your credit reports for any errors and discuss any large debt or change in income with your loan professional. These are some of the first-time home buyer challenges that you can address by working with your loan professional.
There is no minimum credit score or DTI that applies to everyone. If eligibility is your primary concern, a review of first-time home buyer qualifications can help you identify any documentation or financial issues before you make an offer.
Documenting Self-Employed or Variable Income
Self-employed borrowers, commission-based income, and other first-time home buyer challenges related to income documentation can require additional explanation. A lender may request documentation of your business, income, assets, and an explanation of large deposits before approving your loan. The specific requirements can vary based on the loan program and underwriting guidelines.
For eligible self-employed borrowers, Truss Financial Group's bank statement loans may be worth exploring if your income documentation does not reflect your full financial picture. A bank statement is not a qualifying income, but the underwriting guidelines can still consider your business, deposits, expenses, assets, occupancy, and other factors.
Having money in the bank does not always mean that you are approved for a mortgage. This is one of the common challenges faced by first-time home buyers that is worth discussing with a lender before you begin the application process.
Comparing Mortgage Offers Beyond the Interest Rate
A lower interest rate is not always the lowest-cost mortgage. When comparing offers, make sure that you are comparing similar loan amounts, terms, and types.
The CFPB recommends using Loan Estimates to compare offers based on the loan amount, monthly payment, closing costs, cash to close, rate lock, points, and mortgage insurance. The APR can also affect the cost of a mortgage, and points and credits can change the overall value of a mortgage offer.
If one lender offers a lower rate but significantly higher upfront costs, the economics can change if you intend to keep the mortgage for many years. Conventional PMI and FHA mortgage insurance also differ in terms of cancellation and funding.
Affordable mortgage options can help you compare your qualification potential, cash needs, monthly payment, and overall affordability.
Are you ready to compare your financing options? Truss Financial Group can help you explore conventional, FHA, and other mortgage options based on your needs.
Finding a Suitable Home Without Stretching the Budget
Another major first-time home buyer challenge is to find a home that fits your needs and financial situation. Inventory constraints and competitive offers can create pressure to increase your offer. First-time home buyer challenges should not dictate your expectations and needs. Think about the first-time home buyer tips as budget and planning issues – not as negotiation tactics.
Budget for needs, not wants. Factor in the cost of commuting, property taxes, insurance, HOA dues, and any home improvements that you may need to make. A lower-priced home can have a higher monthly payment due to taxes and insurance. A preapproval can help you make an offer, but it is not a loan commitment. It is based on your stated intentions and conditions.
Use first-time home buyer tips to stay within your means – set a firm budget, understand the terms of the contract, and know which contingencies to include. Another first-time home buyer tip is to consider the cost of taxes and insurance before you make an offer. One final first-time home buyer tip is to compare the monthly payment, not the asking price.
Address Inspection and Appraisal Concerns
A home inspection and an appraisal serve two different purposes.
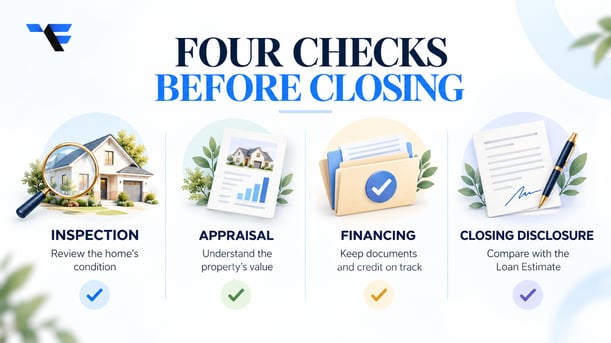
An inspection evaluates the overall condition of the home and can identify needed repairs or improvements. An appraisal is typically an independent evaluation of the value of the home, and the lender will typically rely on the appraisal to understand the collateral value.
If an inspection reveals significant repairs, you can try to negotiate with the seller or cancel the contract, depending on the terms of your offer. If an appraisal comes in lower than the purchase price, you may be able to renegotiate terms or add to your cash reserves.
Review repair estimates, the appraisal, and any financing options with your lender and make sure that you understand your options and rights. Some programs have property requirements that may apply to your loan and home.
Keep Your Financing on Track to Close
- An accepted offer is not a done deal. Staying organized is one of the first-time home buyer tips that can help you keep your financing on track.
- Respond to document requests promptly and avoid applying for new credit, taking out large cash advances, or changing jobs without informing your mortgage professional.
- Additionally, keep track of the rate lock and understand your options if the closing date moves.
- Review the Closing Disclosure before you sign. For most covered mortgages, you must receive the Closing Disclosure at least three business days before you close the deal.
- Compare the figures with the most recent Loan Estimate, and ask your mortgage professional about any differences in loan amount, rate, monthly payment, closing costs, cash to close, points, and credits.
- Complete the final walkthrough and confirm that the property and repairs meet your expectations.
How Truss Financial Group Can Help You Compare Offers
Your mortgage should depend on your income, assets, credit, the home you are buying, your down payment, and your overall budget. One of the final first-time home buyer mistakes to avoid is choosing a mortgage based on the rate.
Truss Financial Group offers conventional and FHA financing and bank statement loan options for eligible self-employed borrowers. The terms can depend on the borrower and the property.
A mortgage broker can help you understand how different mortgage structures affect your upfront costs and monthly payment. Your goal should be a mortgage that you can afford to pay. Understanding the role of a mortgage broker can also help you determine what level of support you need and want.
If you are comparing your financing options, make sure that you understand the full payment amount, cash to close, mortgage insurance, rate lock terms, and closing costs with TFG.
A Final Checklist Before You Make an Offer
- Before you make an offer, make sure that you understand your overall monthly housing budget.
- Save enough cash for the closing costs, moving, repairs, and an emergency fund.
- Review a current preapproval and assumptions. Compare similar Loan Estimates, not just the rate.
- You should also understand the costs of ownership, including the taxes, insurance, and HOA fees.
- Make sure that you understand the terms of the inspection, appraisal, financing, and any other contingencies.
- Review the final Closing Disclosure and compare it with the Loan Estimate.
None of these steps are foolproof, but planning ahead is usually better than scrambling to address first-time home buyer challenges as they arise.
Your Next Steps as a First-Time Home Buyer
The first-time home buyer challenges primarily boil down to one issue – do the home, mortgage, cash needs, and overall budget fit within your means? The solution to first-time home buyer challenges mostly revolves around budget and financing planning.
Start by identifying your primary obstacles. You may need more cash, or you may need to address your credit history, self-employment income, or something else entirely. Once you identify your concerns, gather the necessary documents and meet with a mortgage professional before you make an offer. Truss Financial Group can help you sort through your financing options in the context of your needs and budget.
Your first home does not have to be perfect, but it should fit your budget and financial situation.
FAQs (Frequently Asked Questions)
What mistakes should first-time home buyers avoid?
Common buyer mistakes can include budgeting only for principal and interest, using all of your savings for the down payment, comparing rates without regard for other costs, and skipping an inspection. One of the first-time home buyer mistakes to avoid is to assume that you cannot win by any means. First-time home buyers should always protect their interests.
How do I know how much house I can afford?
You should always budget for the entire housing payment, including principal, interest, taxes, insurance, applicable mortgage insurance, and HOA dues. You should also set aside money for utilities, upkeep, commuting, and living expenses. A lender approval is not necessarily a personal budget.
Do I need a 20 percent down payment to buy my first home?
Not necessarily. There are conventional programs with requirements of less than 20%, and some eligible programs can allow as little as 3%. A reduced down payment can increase the loan amount and potentially add mortgage insurance.
Can I buy a home if I am self-employed?
Yes, but self-employed buyers usually need to provide more detailed income documentation. Depending on the program and documentation, bank statement financing can offer an alternate method of income verification. Self-employment requirements can vary, so it is best to discuss your situation early.
Can a mortgage still be denied after preapproval?
A preapproval is not a loan commitment, and a mortgage can still be denied after a preapproval. The terms of a mortgage can change, depending on the borrower's income, debt, credit, assets, and the property. Any of these factors can change, even after a preapproval.


Discuss your unique requirements
Get direct answers and a roadmap for your future.