The path to homeownership can be complex and daunting, particularly when it comes to mortgage financing. Traditional mortgages often require a host of documents and a strong financial history to qualify. This can be particularly challenging for certain groups of borrowers, such as the self-employed, who might not meet standard underwriting requirements. However, the landscape is changing, thanks to non-QM mortgage brokers who specialize in unique loan products like bank statement mortgages and stated income mortgages. Companies like Truss Financial Group are at the forefront of this revolution, offering flexible loan options for modern borrowers.
What is a Non-QM Mortgage?
The term "non-QM" stands for "non-qualified mortgage," which refers to any mortgage that does not meet the standards set by the Consumer Financial Protection Bureau. Unlike conventional loans, non-QM loans are not backed by government-sponsored entities like Fannie Mae or Freddie Mac.
The Self-Employed Dilemma
Being self-employed offers the freedom of being your own boss but can pose challenges when it comes to qualifying for a mortgage. Traditional mortgage lenders often demand W-2s, tax returns, and a steady income history—documentation that many self-employed individuals might find hard to provide. This is where non-QM mortgage brokers come in. They offer loan products designed to accommodate the financial nuances that come with self-employment.
Bank Statement Mortgage
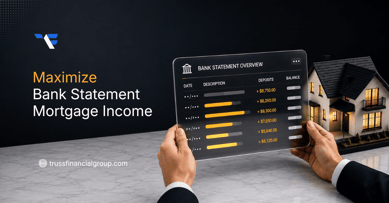
One of the innovative products in the non-QM space is the bank statement mortgage. Instead of requiring traditional income documentation, lenders review 12-24 months of your bank statements to evaluate your cash flow. This is a game-changer for self-employed borrowers, as it offers a more accurate reflection of their earning potential and financial stability.
Stated Income Mortgage
Another popular non-QM loan option is the stated income mortgage. Unlike traditional loans, which require exhaustive financial documentation, stated income mortgages allow the borrower to simply state their income on the loan application without extensive verification. While this product can be risky for the lender, companies like Truss Financial Group have specialized processes to assess the creditworthiness of borrowers, ensuring that the loan is beneficial for both parties.
Why Choose a Non-QM Mortgage Broker?
A non-QM mortgage broker specializes in these types of alternative loan products, navigating borrowers through the complexities of the non-QM landscape. They offer tailored solutions that match the borrower's unique financial situation.
The Role of Truss Financial Group
Truss Financial Group is one of the leading companies in the non-QM space, offering a variety of mortgage options for self-employed borrowers, among others. Their expertise in bank statement mortgages and stated income mortgages makes them a preferred choice for those who struggle to qualify for traditional loans.


 View all states